
Chasing a low rate home loan feels like guesswork until you understand what actually moves the number. A 0.5% difference on a $400,000 loan adds up to over $40,000 in extra interest over 30 years. This guide breaks down the exact levers that shift your rate — and the ones most articles skip entirely.
What Actually Determines Your Mortgage Rate
Your rate isn’t a single decision made by one underwriter. It’s the output of a pricing formula. Lenders use Loan-Level Price Adjustors (LLPAs) tied to your credit score, loan-to-value ratio, and loan type. Two borrowers with identical income can get different rates because their risk profile scores differently on this grid.
Interest Rate vs. APR: Know the Difference Before You Compare Offers
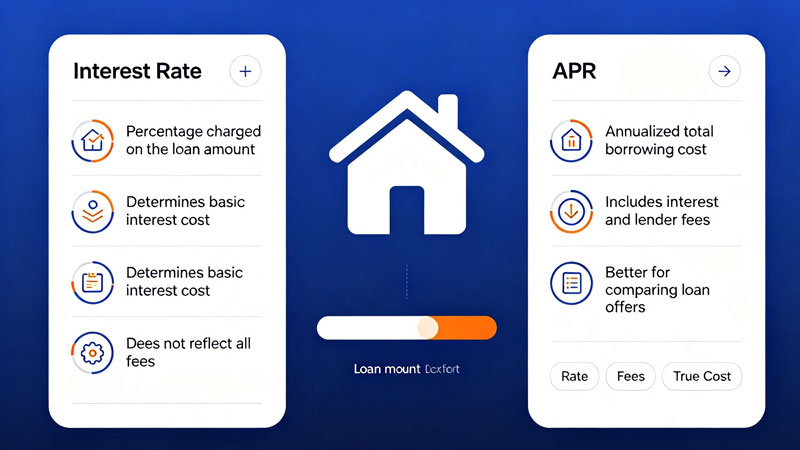
The rate a lender quotes you isn’t the full cost. APR bundles in lender fees, discount points, and mortgage insurance into one annual percentage. A loan with a lower rate but higher fees can carry a higher APR than a competitor’s offer. Always compare APR, not just the headline rate, when shopping lenders.
Strategy 1: Shop Lenders Within a Tight Window
Comparing three to five lenders is standard advice. What matters more is timing. Credit bureaus typically treat multiple mortgage inquiries made within a 14 to 45 day window as a single inquiry for scoring purposes. Spread your applications out over months, and each one dings your score separately.
Ask every lender for a Loan Estimate, not a verbal quote. This three-page federal document standardizes the numbers so you’re comparing apples to apples — rate, APR, closing costs, and monthly payment side by side.
Compare current mortgage rates
Strategy 2: Know Your Credit Score Tier
Lenders don’t treat credit scores as a sliding scale. They price in bands. A borrower at 760+ typically lands in the top pricing tier. Drop to the 620-659 range, and the rate premium can run a full percentage point or more, depending on loan type and down payment.
| Credit Score Range | Typical Rate Impact |
|---|---|
| 760+ | Best available pricing |
| 700-759 | Slightly above best tier |
| 660-699 | Moderate premium |
| 620-659 | Significant premium |
Before applying, pull your report and dispute errors. Pay down revolving balances below 30% utilization. Don’t open new credit lines in the months before your application — even a single hard inquiry can nudge your tier down.
Credit score impact on loan pricing
Strategy 3: Fix Your Debt-to-Income Ratio First
Lenders calculate two DTI figures: front-end (housing costs only) and back-end (all monthly debt, including the proposed mortgage). Most conventional lenders cap back-end DTI around 43%, though some programs stretch to 50% with compensating factors like strong reserves.
Say your total monthly debts run $2,000 and your gross income is $5,000. Your DTI sits at 40%. Pay off a car loan or bump your income, and that ratio drops fast — often faster than waiting on a credit score to climb.
Cash reserves matter here too. Lenders view two to six months of reserves as a buffer against risk, and it can offset a borderline DTI or credit score in their pricing decision.
Strategy 4: Structure Your Down Payment Around LTV Breakpoints
Pricing tiers shift at specific loan-to-value thresholds — commonly at 80%, 90%, and 95%. Crossing from 78% to 80% LTV by adding a few thousand dollars to your down payment can drop you into a better pricing bracket, not just save on mortgage insurance.
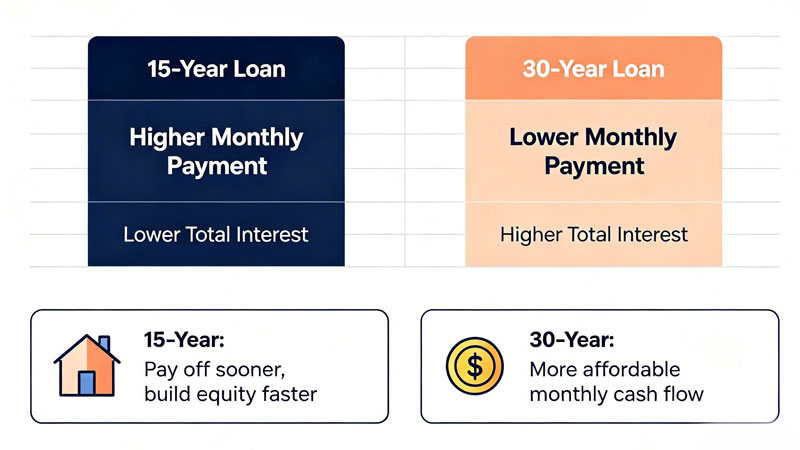
Run the math on loan term too. A 15-year loan usually carries a meaningfully lower rate than a 30-year loan, since the lender’s risk window is shorter. The trade-off is a higher monthly payment — worth comparing side by side before you commit.
Strategy 5: Buy Down Your Rate the Smart Way
Discount points cost 1% of your loan amount upfront and typically shave a fraction of a percent off your rate. Calculate your break-even point before buying: divide the point cost by your monthly savings. If you won’t stay in the home past that point, skip it.
Temporary buydowns (2-1 or 3-2-1 structures) lower your rate for the first one to three years, then step up to the note rate. These work well when a seller or builder covers the cost, or when you expect your income to rise before the full rate kicks in.
A no-closing-cost refinance rolls fees into the rate instead of cash at closing. You’ll pay a slightly higher rate in exchange for zero upfront cost — a reasonable trade if you don’t plan to hold the loan for more than a few years.
Strategy 6: Time Your Rate Lock Correctly
A rate lock holds your quoted rate for 30 to 60 days while your loan processes. Lock too early, and you might miss a rate drop. Wait too long, and a rate spike hits you at the worst moment.
If your closing slips past the lock period, expect an extension fee — often a small daily or flat charge depending on the lender. Ask about float-down provisions upfront: some lenders let you drop to a lower rate once, for a fee, if the market moves in your favor before closing.
Strategy 7: Refinance When the Math Actually Works
The old “0.75% to 1% rule” for refinancing is a rough guide, not a rule. Run your actual break-even: divide closing costs by your monthly savings. If you recoup the cost before you plan to sell or refinance again, it’s worth doing — regardless of whether the rate drop hits an arbitrary threshold.
Loan type shapes your refinance path. FHA borrowers may qualify for a Streamline Refinance with minimal documentation. VA loan holders can use an Interest Rate Reduction Refinance Loan (IRRRL). Conventional borrowers generally need a 620+ score and enough equity to avoid PMI.
Which Strategy Fits Your Situation?
- First-time buyer, average credit: Focus on credit tier improvement and down payment assistance programs before rate shopping.
- Refinancing an existing loan: Run the break-even math first — don’t refinance on rate drop alone.
- Self-employed: Get two years of tax returns and P&L statements ready before applying; documentation delays cost you rate-lock time.
- Lower credit score: Look into FHA or state first-time buyer programs designed for accessible pricing tiers.
Frequently Asked Questions
What credit score do I need for the lowest mortgage rate?
Most lenders reserve top-tier pricing for scores of 760 or higher. You can still get a competitive rate in the 700s, but the gap widens below 660.
Is it better to buy points or make a larger down payment?
It depends on your timeline. Points pay off if you stay long enough to hit the break-even point. A larger down payment lowers your LTV permanently and cuts PMI, which often delivers steadier savings.
Does refinancing hurt my credit score?
A refinance application triggers a hard inquiry, which can dip your score a few points temporarily. The impact is usually minor and short-lived compared to the long-term savings from a lower rate.
What’s the difference between a rate lock and a float-down?
A rate lock freezes your rate for a set period. A float-down is an add-on option that lets you drop to a lower rate once if the market improves before closing, usually for an extra fee.
Disclaimer: This article is for informational purposes only and does not constitute financial, legal, or investment advice. Mortgage products, rates, and qualification requirements vary by lender and change over time. Consult a licensed mortgage professional or financial advisor before making borrowing decisions.